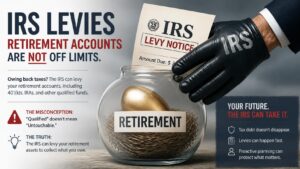
Few IRS fears hit harder than this one. For many taxpayers, retirement accounts represent years—or decades—of disciplined saving. So when IRS debt enters the picture, a common and deeply emotional question arises: Can the IRS take my 401(k) or IRA?
The short answer is yes. Understanding when retirement accounts are at risk (and when they’re not) can help you avoid panic, bad decisions, and costly mistakes.
Why Retirement Accounts Feel “Off Limits”
Most people assume retirement accounts are protected because:
- They’re intended for future income
- Other creditors often can’t touch them
- They may be governed by federal or employer plans
While those assumptions hold true for many private creditors, the Internal Revenue Service plays by different rules.
What Authority the IRS Actually Has
The IRS has the legal power to levy retirement accounts—but only after meeting strict requirements. These include:
- Providing proper notice
- Allowing appeal rights
- Demonstrating that other collection options are insufficient
Even then, retirement account levies are generally considered a last resort, not a first move.
In most cases, the IRS prefers easier collection methods like wage garnishments, bank levies, or payment plans.
The Biggest Mistake Taxpayers Make Out of Fear
Fear often drives people to drain retirement accounts themselves to “get ahead” of the IRS. This can be disastrous.
Early withdrawals may trigger:
- Income taxes
- Penalties
- Loss of long-term financial security
Worse, the IRS may still pursue additional collection afterward—leaving you with less protection and fewer options.
How Proper Strategy Protects Retirement Savings
A strategic approach focuses on:
- Stopping enforcement before it escalates
- Using payment plans or hardship status
- Structuring resolutions that preserve protected assets
- Communicating with the IRS before extreme measures are considered
At Ron Friedman CPA, we help taxpayers understand real risk versus perceived risk—and take action before fear-driven decisions cause irreversible harm.
Final Thought: The IRS Can—but Usually Doesn’t
Yes, the IRS can take retirement accounts. But in practice, it’s uncommon and usually avoidable with early, informed action.
If you owe the IRS and are worried about your 401(k), IRA, or pension, guessing can be expensive. Ron Friedman CPA can review your situation, explain your true exposure, and help you protect what you’ve worked so hard to build.
Contact Ron Friedman CPA today for a confidential consultation—and replace fear with facts before the IRS makes the next move.


