914 Tax

Pay My Invoice Now 914-712-6919
  • Home
  • About
  • Tax Solutions
    • Asset Seizures
    • Audit Representation
    • Delinquent Returns
    • Federal Tax Liens
    • Innocent/Injured Spouse Relief
    • Installment Agreements
    • Levies and Garnishments
    • Offer in Compromise
    • Payroll Tax Problems
  • Tax Preparation
  • Testimonials
  • Tax Tips
  • Contact Us
  • Home
  • /
  • back taxes

Can the IRS Take Your Retirement Accounts?

October 15, 2026

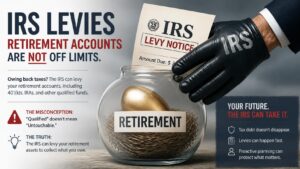
Few IRS fears hit harder than this one. For many taxpayers, retirement accounts represent years—or decades—of disciplined saving. So when IRS debt enters the picture, a common and deeply emotional question arises: Can the IRS take my 401(k) or IRA?

The short answer is yes. Understanding when retirement accounts are at risk (and when they’re not) can help you avoid panic, bad decisions, and costly mistakes.

Why Retirement Accounts Feel “Off Limits”

Most people assume retirement accounts are protected because:

  • They’re intended for future income
  • Other creditors often can’t touch them
  • They may be governed by federal or employer plans

While those assumptions hold true for many private creditors, the Internal Revenue Service plays by different rules.

What Authority the IRS Actually Has

The IRS has the legal power to levy retirement accounts—but only after meeting strict requirements. These include:

  • Providing proper notice
  • Allowing appeal rights
  • Demonstrating that other collection options are insufficient

Even then, retirement account levies are generally considered a last resort, not a first move.

In most cases, the IRS prefers easier collection methods like wage garnishments, bank levies, or payment plans.

The Biggest Mistake Taxpayers Make Out of Fear

Fear often drives people to drain retirement accounts themselves to “get ahead” of the IRS. This can be disastrous.

Early withdrawals may trigger:

  • Income taxes
  • Penalties
  • Loss of long-term financial security

Worse, the IRS may still pursue additional collection afterward—leaving you with less protection and fewer options.

How Proper Strategy Protects Retirement Savings

A strategic approach focuses on:

  • Stopping enforcement before it escalates
  • Using payment plans or hardship status
  • Structuring resolutions that preserve protected assets
  • Communicating with the IRS before extreme measures are considered

At Ron Friedman CPA, we help taxpayers understand real risk versus perceived risk—and take action before fear-driven decisions cause irreversible harm.

Final Thought: The IRS Can—but Usually Doesn’t

Yes, the IRS can take retirement accounts. But in practice, it’s uncommon and usually avoidable with early, informed action.

If you owe the IRS and are worried about your 401(k), IRA, or pension, guessing can be expensive. Ron Friedman CPA can review your situation, explain your true exposure, and help you protect what you’ve worked so hard to build.

Contact Ron Friedman CPA today for a confidential consultation—and replace fear with facts before the IRS makes the next move.
October 11, 2026Categories: back taxes, income taxes, IRS, retirement accounts, retirement planning, Tax Resolution Strategies

What Happens When the IRS Assigns a Revenue Officer to Your Case

October 6, 2026

For a year, maybe longer, your tax problem showed up in the mailbox. Computer-printed notices. A balance that grew every month. A toll-free number with a long hold and a different person every time.

Then a letter arrives with an individual’s name on it, a direct phone line, and a date you’re expected to meet.

Your case has been assigned to a Revenue Officer. The automated phase is over.

What a Revenue Officer Does

A Revenue Officer works in IRS field collection. An auditor questions the numbers on a return. A Revenue Officer treats the number as final and collects it, and gets your unfiled returns filed while they’re at it.

They carry a caseload. They are measured on closing cases. And they have authority to act without asking a computer for permission, which is what separates this stage from every notice that came before it.

Why Your Case Got Here

Cases move to field collection for reasons. The common ones:

  • The balance is large enough to justify an employee’s time
  • Payroll taxes are involved, and unpaid trust fund liabilities get priority
  • Returns are unfiled
  • Earlier notices went unanswered, or an installment agreement defaulted
  • A business is still operating and still falling behind

What Arrives First

Usually Letter 725-B, which schedules a meeting, along with Form 9297, Summary of Taxpayer Contact. Form 9297 lists what the Revenue Officer wants and the date they want it by. That date is typically measured in days.

The IRS ended most unannounced Revenue Officer visits in July 2023, so a knock at the door is now rare. It still happens when the IRS is serving a summons or seizing property. Otherwise, anyone showing up unannounced claiming to be from the IRS is a reason to pick up the phone and call your representative.

Expect requests for a completed Form 433-A or 433-B, bank statements, proof of current estimated payments or federal tax deposits, and any returns that haven’t been filed.

What Happens If You Don’t Respond

  • A Notice of Federal Tax Lien gets filed
  • Bank accounts, wages, and accounts receivable get levied
  • Your records, your bank, or your customers get summonsed
  • You get interviewed on Form 4180 so the IRS can decide who is personally responsible for unpaid payroll taxes, then assess the Trust Fund Recovery Penalty against them
  • Property gets seized and sold, in the hardest cases

What’s Still Available

A Revenue Officer assignment does not close the door on resolution. Depending on the numbers, the options include an installment agreement, a partial pay installment agreement, currently not collectible status, an offer in compromise, and penalty relief.

All of them share one prerequisite: compliance. Missing returns filed. Current deposits and estimated payments actually being made. No Revenue Officer is going to approve a resolution for a taxpayer who is still falling behind, and neither is their manager.

Why the First Conversation Matters

Revenue Officers document everything. What you say on the first call goes into the case history and follows the case from there. That includes a financial statement filled out wrong, an offhand comment about a relative’s bank account, or a promise you can’t keep.

Once a Form 2848 is on file, the Revenue Officer works with your representative instead of you.

Ron Friedman CPA represents taxpayers whose cases are in IRS field collection. If a Revenue Officer has contacted you, or you think your case is heading that way, call 914.712.6919 or visit www.914tax.com for a confidential consultation. Your options are better before the deadlines start passing.

September 6, 2026Categories: back taxes, business owners, business taxes, Payment plans, Revenue Officer

Do Your Job, Do No Harm

October 1, 2026

A woman recently came to me with an IRS debt that had followed her for more than a decade.

She was holding a recent collection notice and a Notice of Federal Tax Lien showing a balance close to seven figures. She was frightened and looking for a way out.

Initially, I was excited to help. Then I began reviewing the records.

Understanding the Tax Debt

Before recommending a solution, I needed to understand the problem.

I reviewed the taxpayer’s IRS transcripts to determine:

  • How the debt arose;
  • When the tax was assessed;
  • Whether the balance was accurate;
  • Whether bankruptcy affected the collection period; and
  • How much longer the IRS had to collect the debt.

The transcripts showed that the taxpayer had filed for bankruptcy. That is not unusual in a tax-resolution matter. Bankruptcy can affect both the collectibility of a tax debt and the time the IRS has to collect it.

In this case, however, the bankruptcy records revealed something more troubling.

A Six-Figure Refund

Years earlier, the taxpayer had filed an income tax return claiming an unusually large refund. The IRS processed the return and issued her a six-figure payment.

The IRS later determined that the refund was improper. It sought repayment of the money, along with interest, penalties, and other charges.

The bankruptcy records also identified an organization accused of promoting tax-defier theories. The available information suggested that the questionable return may have been connected to positions promoted by that organization.

This case highlights an important fact:

Receiving a refund does not mean the IRS has examined and approved the return.

The IRS may process a return and issue a refund before reviewing the claims made on it. If the refund is later disallowed, the taxpayer may be required to repay it—with substantial additions.

What initially appeared to be a financial windfall had become a crushing tax debt.

Bankruptcy Did Not Solve the Problem

The taxpayer apparently believed bankruptcy would protect her from IRS collection.

Bankruptcy can be a valuable tax-resolution tool, but it does not eliminate every tax liability. The result depends on the type of debt, the filing and assessment dates, prior collection events, and the circumstances that created the liability.

When bankruptcy failed to provide the relief she expected, the IRS resumed collection activity.

The taxpayer was now in a serious bind. She wanted to know whether the debt could be resolved through an offer in compromise.

The Professional’s Responsibility

Our job is to investigate the facts, explain the risks and identify the lawful options. We can challenge an incorrect assessment, oppose an improper collection action and negotiate an appropriate resolution.

We cannot make the history of a tax debt disappear.

Sometimes effective representation means fighting aggressively for the taxpayer. At other times, it means explaining that the solution the taxpayer wants may not be available.

That is the meaning behind my professional philosophy:

Do Your Job, Do No Harm

Advocate for the client, but do not mislead the client.

Explore every lawful remedy, but do not reinforce the conduct that created the problem.

Taxpayers should be cautious of anyone promising:

  • A secret way to avoid federal income taxes;
  • An enormous refund based on an unconventional theory;
  • Guaranteed protection through bankruptcy; or
  • A settlement with the IRS for “pennies on the dollar.”

When you hear someone mentioning one of these ideas, encourage that person to obtain competent advice before the situation becomes worse.

Ron Friedman CPA helps taxpayers understand their IRS collection options and build a strategy around their actual financial situation.

If you or someone you know owes back taxes, has been contacted by an IRS revenue officer, or is worried about IRS collection action, call Ron Friedman CPA at 914.712.6919 for a consultation.

September 7, 2026Categories: audit, back taxes, Bankruptcy, income taxes

When You Can’t Pay the IRS All at Once: Installment Agreements Explained

August 24, 2026

Owing the IRS doesn’t always mean you have to pay everything immediately. For many taxpayers, an IRS Installment Agreement provides a practical way to resolve tax debt over time while avoiding aggressive collection actions.

At Ron Friedman CPA, we help taxpayers set up installment agreements that are realistic, sustainable, and strategically structured.

What Is an IRS Installment Agreement?

An Installment Agreement is a formal payment plan with the Internal Revenue Service that allows you to pay your tax balance in monthly payments instead of a lump sum.

Once approved, the IRS generally pauses enforcement actions such as bank levies and wage garnishments—as long as payments are made on time and you stay compliant going forward.

Example: How an Installment Agreement Works

Chris owed $32,000 in back taxes after falling behind during a slow year in his business. He couldn’t afford to pay the balance in full but had steady income.

With professional guidance, Chris submitted the required information and negotiated a monthly payment that fit his budget. The IRS approved the Installment Agreement, stopping collection actions and allowing him to pay down the debt over time.

How We Can Help

Not all Installment Agreements are the same—and agreeing to the wrong payment can create long-term problems. Ron Friedman CPA helps by reviewing your IRS account, determining the right type of agreement, negotiating affordable payments, and communicating directly with the IRS.

If you owe the IRS and need a manageable way forward, contact Ron Friedman CPA today for a confidential consultation to see whether an Installment Agreement is right for you.

August 14, 2026Categories: back taxes, income taxes, Installment Agreements, IRS, Payment plans

The IRS Doesn’t Need to Sue You—Here’s How They Collect Without Court

August 17, 2026

Many taxpayers assume the IRS works like other creditors—that if things get serious, there will be a lawsuit, a court date, or a judge involved. That assumption is not only wrong, it’s dangerous.

The Internal Revenue Service has extraordinary collection powers that allow it to take money directly from you without ever going to court. Understanding how this works can help you recognize when the risk is real—and why waiting for a lawsuit is often too late.

Why the IRS Doesn’t Need Court Approval

Unlike private creditors, the IRS is granted administrative collection authority under federal law. That means once certain notice requirements are met, the IRS can enforce collection actions on its own.

There is no judge, no lawsuit, and no courtroom warning shot. By the time taxpayers realize enforcement has begun, the money is often already gone.

Bank Levies: When Accounts Are Frozen and Drained

One of the IRS’s most powerful tools is a bank levy. When issued, your bank is required to freeze your account—often without advance warning.

After a short holding period, the funds are sent directly to the IRS. This can include checking, savings, and certain investment accounts. For many taxpayers, this is the moment the situation becomes a full-blown financial emergency.

Wage Garnishments: Ongoing, Not One-Time

IRS wage garnishments work differently than most people expect. Instead of taking a percentage, the IRS allows you to keep only a small exempt amount—then takes the rest of your paycheck.

This continues every pay period until the debt is resolved or the garnishment is released. Waiting for a lawsuit means missing the chance to prevent this from starting.

Offsets: Taking Money You Were Expecting

The IRS can also collect by offsetting money owed to you. This commonly includes:

  • Federal and state tax refunds
  • Certain government payments

Many taxpayers are surprised when expected refunds disappear without explanation. By the time they ask why, the funds are already applied to the tax debt.

Asset Seizures and Other Enforcement Tools

In more serious cases, the IRS can seize assets such as vehicles, business equipment, or other property. While less common, these actions are fully legal and don’t require court involvement.

The longer a case goes unaddressed, the more likely aggressive tools are used.

The Most Dangerous Assumption of All

Waiting for the IRS to “sue” before taking action gives the IRS exactly what it needs: time. Silence is interpreted as noncooperation, not inability.

Ironically, many taxpayers who truly can’t afford to pay qualify for protection—but only if they act before enforcement begins.

Final Thought: The IRS Acts First—Courts Come Later (If at All)

If you owe the IRS, enforcement doesn’t start with a lawsuit. It starts with notices—and ends with levies, garnishments, and offsets if nothing is done.

At Ron Friedman CPA, we help taxpayers stop IRS collection actions, understand their rights, and take control before enforcement causes lasting damage.

If you’re receiving IRS notices or worried about what might happen next, contact Ron Friedman CPA today for a confidential consultation. Waiting for court could cost you far more than you expect.

August 14, 2026Categories: back taxes, income taxes, IRS, levy

Settling Tax Debt for Less: Offer in Compromise Explained

July 16, 2026

An Offer in Compromise (OIC) is one of the most well-known—and most misunderstood—IRS resolution options. While it can allow some taxpayers to settle their tax debt for less than the full amount owed, qualification is far more limited than most advertisements suggest.

At Ron Friedman CPA, we help taxpayers determine whether an Offer in Compromise is realistic and handle the process the right way.

What Is an Offer in Compromise?

An Offer in Compromise is an agreement where the Internal Revenue Service agrees to accept less than the full balance owed when it believes it cannot reasonably collect the full amount.

Approval is based on:

  • Income and allowable living expenses
  • Assets and available equity
  • Ability to pay now and in the future
  • Compliance with filing and payment requirements

It’s not about how much you owe—it’s about what the IRS believes it can collect.

Example: How an Offer in Compromise Works

Robert owed $126,000 in back taxes after several difficult years in business. Although he was working, his income barely covered basic expenses and he had little usable asset equity.

With professional assistance, Robert submitted a detailed financial analysis showing the IRS was unlikely to collect the full balance. The IRS accepted his Offer in Compromise, allowing him to settle the debt for a fraction of what he owed.

How We Can Help

Offers in Compromise are frequently denied when submitted incorrectly or without proper analysis. Ron Friedman CPA helps by evaluating eligibility, preparing accurate financial disclosures, submitting a strong offer, and communicating with the IRS throughout the process.

If you’re carrying IRS debt and wondering whether a settlement is truly possible, contact Ron Friedman CPA today for a confidential consultation to find out if an Offer in Compromise makes sense for your situation.

July 8, 2026Categories: back taxes, Offer in Compromise

I Owe the IRS but Can’t Afford to Pay—What Really Happens Next

July 9, 2026

When someone owes the IRS and can’t afford to pay, the most common response is…doing nothing. Not because they don’t care—but because they’re overwhelmed, scared, or unsure what options exist. Unfortunately, silence doesn’t pause the process. It starts one.

Here’s a plain-English walkthrough of what the Internal Revenue Service typically does when a taxpayer takes no action.

Step 1: The Letters Start (And Slowly Escalate)

The IRS begins with a series of notices explaining the balance due. Early letters are informational and relatively mild. They outline what’s owed, how to pay, and what happens if the balance remains unpaid.

Many taxpayers ignore these notices hoping the issue will resolve itself. It won’t. Each letter moves the account closer to enforced collection—even if months pass between notices.

Step 2: Penalties and Interest Quietly Grow

While nothing seems to be happening, penalties and interest continue to accrue daily. A manageable balance can quietly grow into something far more serious.

This is where many taxpayers lose ground without realizing it. The IRS doesn’t need to act aggressively for the debt to get worse—it grows automatically.

Step 3: The IRS Files a Tax Lien

If the balance remains unpaid, the IRS may file a Notice of Federal Tax Lien. This publicly secures the government’s interest in your property and future assets.

A lien can:

  • Complicate refinancing or selling property
  • Signal that enforcement is escalating

At this stage, the IRS still hasn’t taken your money—but it has positioned itself to do so.

Step 4: Levies and Garnishments Begin

If no action is taken after lien and final notice stages, the IRS may begin levies. This is where things become immediately disruptive.

Levies can include:

  • Freezing and taking funds from bank accounts
  • Garnishing wages
  • Seizing certain assets

Once levies start, financial flexibility shrinks fast—and stopping them becomes harder.

Step 5: The IRS Assumes You’re Choosing Not to Pay

The longer nothing happens, the more the IRS assumes the issue isn’t inability—it’s avoidance. That assumption changes how your case is treated and reduces flexibility.

Ironically, many taxpayers who truly can’t afford to pay qualify for relief—but only if they act before enforcement hardens the IRS’s position.

What Most People Don’t Realize

The IRS actually has options for people who can’t pay—but it rarely offers them proactively. Relief usually requires:

  • Filing required returns
  • Demonstrating financial hardship
  • Requesting protection or structured resolution

Doing nothing guarantees none of that happens.

Final Thought: Inaction Is a Decision—And It’s the Worst One

If you owe the IRS and can’t afford to pay, ignoring the problem doesn’t make it disappear. It simply hands control to the IRS and allows the situation to escalate on its own timeline.

At Ron Friedman CPA, we help taxpayers interrupt this process, understand what the IRS is likely to do next, and take action before enforcement causes real damage.

If you’re overwhelmed by IRS debt and unsure what to do, contact Ron Friedman CPA today for a confidential consultation. Knowing your options early can prevent months—or years—of unnecessary stress.

July 8, 2026Categories: back taxes, business taxes, income taxes, IRS, IRS Fresh Start Program, Offer in Compromise

Influencer Indicted for Allegedly Underreporting More Than $1.1 Million in Income

June 25, 2026

A social media influencer from Phoenix is facing federal tax charges after prosecutors alleged he failed to report substantial income from his online business.

Charles Lewis Davis, owner of Forever Investments LLC, was indicted by a federal grand jury on two counts of making false statements on his tax returns. According to the indictment, Davis allegedly failed to tell his tax preparer about additional income earned through videos posted on YouTube, Facebook, Instagram, and other platforms.

Prosecutors claim Davis underreported income by:

$807,142 in 2020
$390,566 in 2021

The indictment also alleges the unreported funds were held in personal and business bank accounts, brokerage accounts, and cryptocurrency accounts.

Davis pleaded not guilty at his initial court appearance. If convicted, making a false statement on a tax return carries a maximum penalty of three years in prison and a $250,000 fine.

This case is a reminder that income from social media, side businesses, gig work, investments, and cryptocurrency is still taxable income. Even if funds move through multiple accounts or platforms, the IRS has tools to trace income and compare it against what was reported.

For business owners, influencers, contractors, and self-employed taxpayers, accurate reporting is critical. Relying on a tax preparer does not protect you if important information is withheld or records are incomplete.

If you have unfiled returns, unreported income, IRS notices, or concerns about past tax filings, don’t ignore the problem. Contact Ron Friedman CPA today for a free consultation. We’ll review your situation, explain your options, and help you take the next step toward resolving your tax issue.

June 11, 2026Categories: audit, back taxes, income taxes, Scammers, Self Employed

When IRS Penalties Aren’t Fair: Reasonable Cause Penalty Abatement

June 18, 2026

IRS penalties can add up quickly—often turning a manageable tax balance into an overwhelming problem. In some situations, the IRS may remove penalties entirely through Reasonable Cause Penalty Abatement.

At Ron Friedman CPA, we help taxpayers determine whether their circumstances qualify and present their case clearly and effectively.


What Is Reasonable Cause Penalty Abatement?

Reasonable Cause Penalty Abatement allows the Internal Revenue Service to remove penalties when a taxpayer can show they exercised ordinary care but were unable to comply due to circumstances beyond their control.

This relief commonly applies to penalties for:

  • Late filing
  • Late payment
  • Failure to deposit taxes

Approval depends on facts, documentation, and how the situation is explained.


Example: How Reasonable Cause Works

After a serious medical emergency, Tom fell behind on filing and paying his taxes. By the time he recovered, IRS penalties had significantly increased his balance.

With professional assistance, Tom submitted medical documentation and a written explanation showing the situation was unavoidable. The IRS agreed that reasonable cause existed and removed the penalties, substantially reducing what he owed.

How We Can Help

Reasonable Cause requests are not automatic and are often denied when handled improperly. Ron Friedman CPA helps by evaluating your situation, preparing a strong narrative with supporting documentation, and communicating directly with the IRS.

If IRS penalties are making your tax problem worse, contact Ron Friedman CPA today for a confidential consultation to see if Reasonable Cause Penalty Abatement may be available to you.

June 11, 2026Categories: Abatement, back taxes, income taxes, Penalties, Tax penalties

How IRS Collection Actions Can Shut Down Your Business Overnight

June 11, 2026

Many business owners assume IRS collection problems move slowly and that there will be plenty of time to address tax issues before anything serious happens. Unfortunately, that assumption can be costly.

The IRS has powerful collection tools that can significantly disrupt business operations without ever filing a lawsuit or appearing before a judge. Once collection activity escalates, access to the cash needed to operate your business can disappear quickly, creating an immediate financial crisis.

When the IRS Freezes Your Bank Account

One of the most damaging collection actions available to the IRS is a bank levy. When a levy is issued, the bank is required to freeze funds in the account and hold them for the IRS.

For many businesses, operating cash is used daily to meet payroll, pay rent, purchase inventory, and cover other essential expenses. Losing access to those funds—even temporarily—can make it impossible to continue normal operations.

A business can be profitable and still find itself in serious trouble if the cash needed to operate becomes inaccessible.

The IRS Can Collect From More Than Your Bank Account

Many business owners are surprised to learn that the IRS is not limited to levying bank accounts. The agency can also pursue funds owed to the business by third parties.

For example, the IRS may issue levies to customers who owe your business money or to payment processors handling transactions on your behalf. Instead of receiving payment for completed work, your customers or payment providers may be required to send those funds directly to the IRS.

For businesses that depend on steady cash flow, the impact can be immediate and severe.

The Domino Effect of Cash Flow Disruption

Once IRS collection actions begin, the consequences often extend far beyond the tax debt itself.

A sudden interruption in cash flow can result in:

  • Missed payroll obligations
  • Late rent or loan payments
  • Strained vendor relationships
  • Reduced customer confidence
  • Operational disruptions that threaten the future of the business

In many cases, it is not the amount of the tax debt that causes the greatest damage—it is the loss of access to the cash needed to keep the business running.

Why Waiting Makes Matters Worse

Most IRS enforcement actions do not occur without warning. Businesses typically receive multiple notices before collection activity escalates.

However, ignored notices, unfiled returns, and unresolved payroll tax liabilities significantly increase the likelihood of aggressive enforcement. By the time a Revenue Officer becomes involved, the IRS is often focused on collecting the liability rather than simply requesting compliance.

The longer a business waits to address the problem, the fewer options are generally available.

Early Action Can Protect Your Business

The good news is that many IRS collection actions can be prevented or resolved before they threaten business operations.

Early intervention may allow a business to:

  • Prevent or release levies
  • Protect operating accounts
  • Establish payment arrangements
  • Preserve payroll and vendor relationships
  • Create time to stabilize operations

The key is acting before enforcement reaches a crisis point.

Final Thoughts

The IRS possesses broad collection authority, and those powers can affect a business much faster than many owners realize. If your business has unresolved tax liabilities, payroll tax issues, or has begun receiving collection notices, now is the time to act.

Protecting cash flow is critical. Once collection actions begin disrupting operations, recovery becomes significantly more difficult. Addressing the problem early can help preserve your business while creating a path toward resolving the underlying tax debt.

At Ron Friedman, CPA, we help business owners stop IRS collection actions, protect cash flow, and build strategies that keep operations alive while resolving tax debt.

Contact Ron Friedman, CPA today for a confidential consultation—before the IRS decides when your business stops running.

June 11, 2026Categories: back taxes, business owners, business taxes, filing taxes, IRS, levy

Posts pagination

Page 1 Page 2 … Page 4 Next page

Recent Posts

  • When Paying the IRS Isn’t Possible: A Look at CNC Status
  • Can the IRS Take Your Retirement Accounts?
  • What Happens When the IRS Assigns a Revenue Officer to Your Case
  • Do Your Job, Do No Harm
  • The Coming Collection Squeeze

Archives

  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • July 2022
  • June 2022
  • May 2022
  • February 2022
  • January 2022
  • December 2021
  • November 2021
  • October 2021
  • August 2021
  • July 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • December 2020
  • October 2020
  • September 2020
  • August 2020
  • June 2020
  • January 2020
  • August 2019
  • July 2019
  • October 2016
  • September 2016
  • March 2016

Ron Friedman Tax Relief Pro

150 White Plains Road
Suite 310, Tarrytown, NY 10591
Tel: (914) 712-6919
Fax: (914) 631-0939
ron@ronfriedmancpa.com

Recent Posts

  • When Paying the IRS Isn’t Possible: A Look at CNC Status
  • Can the IRS Take Your Retirement Accounts?
  • What Happens When the IRS Assigns a Revenue Officer to Your Case

Servicing Areas

Westchester County, NY, Fairfield Cty, CT, New York City, The Bronx, Brooklyn, Queens, Staten Island, and surrounding areas.

IRS Circular 203 Disclosure: Any tax advice on this website (or any attachment hereto) is not intended or written to be used by any taxpayer for the purpose of avoiding penalties that may be imposed under U.S. tax law.
Facebook LinkedIn
© 2026 914 Tax. All Rights Reserved.