914 Tax

Pay My Invoice Now 914-712-6919
  • Home
  • About
  • Tax Solutions
    • Asset Seizures
    • Audit Representation
    • Delinquent Returns
    • Federal Tax Liens
    • Innocent/Injured Spouse Relief
    • Installment Agreements
    • Levies and Garnishments
    • Offer in Compromise
    • Payroll Tax Problems
  • Tax Preparation
  • Testimonials
  • Tax Tips
  • Contact Us
  • Home
  • /
  • Tax Resolution Strategies

Can the IRS Take Your Retirement Accounts?

October 15, 2026

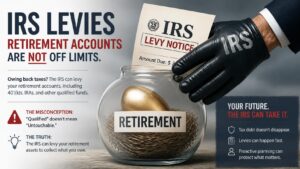
Few IRS fears hit harder than this one. For many taxpayers, retirement accounts represent years—or decades—of disciplined saving. So when IRS debt enters the picture, a common and deeply emotional question arises: Can the IRS take my 401(k) or IRA?

The short answer is yes. Understanding when retirement accounts are at risk (and when they’re not) can help you avoid panic, bad decisions, and costly mistakes.

Why Retirement Accounts Feel “Off Limits”

Most people assume retirement accounts are protected because:

  • They’re intended for future income
  • Other creditors often can’t touch them
  • They may be governed by federal or employer plans

While those assumptions hold true for many private creditors, the Internal Revenue Service plays by different rules.

What Authority the IRS Actually Has

The IRS has the legal power to levy retirement accounts—but only after meeting strict requirements. These include:

  • Providing proper notice
  • Allowing appeal rights
  • Demonstrating that other collection options are insufficient

Even then, retirement account levies are generally considered a last resort, not a first move.

In most cases, the IRS prefers easier collection methods like wage garnishments, bank levies, or payment plans.

The Biggest Mistake Taxpayers Make Out of Fear

Fear often drives people to drain retirement accounts themselves to “get ahead” of the IRS. This can be disastrous.

Early withdrawals may trigger:

  • Income taxes
  • Penalties
  • Loss of long-term financial security

Worse, the IRS may still pursue additional collection afterward—leaving you with less protection and fewer options.

How Proper Strategy Protects Retirement Savings

A strategic approach focuses on:

  • Stopping enforcement before it escalates
  • Using payment plans or hardship status
  • Structuring resolutions that preserve protected assets
  • Communicating with the IRS before extreme measures are considered

At Ron Friedman CPA, we help taxpayers understand real risk versus perceived risk—and take action before fear-driven decisions cause irreversible harm.

Final Thought: The IRS Can—but Usually Doesn’t

Yes, the IRS can take retirement accounts. But in practice, it’s uncommon and usually avoidable with early, informed action.

If you owe the IRS and are worried about your 401(k), IRA, or pension, guessing can be expensive. Ron Friedman CPA can review your situation, explain your true exposure, and help you protect what you’ve worked so hard to build.

Contact Ron Friedman CPA today for a confidential consultation—and replace fear with facts before the IRS makes the next move.
October 11, 2026Categories: back taxes, income taxes, IRS, retirement accounts, retirement planning, Tax Resolution Strategies

When You Can Pay Something, But Not Everything: The Partial Pay Installment Agreement

September 17, 2026

Some taxpayers can’t afford the payment on a standard IRS installment agreement. The monthly number is real, and it’s still more than they have.

A Partial Pay Installment Agreement, or PPIA, exists for that gap. It lets you pay what your financials show you can afford, even when those payments will never satisfy the full balance.

How a PPIA Works

The IRS generally has ten years to collect an assessed tax. That deadline is the Collection Statute Expiration Date, or CSED. A standard installment agreement pays the balance in full before the CSED runs. A PPIA doesn’t. You pay the affordable amount, the statute expires, and the unpaid balance expires with it.

The IRS agrees to this because your financial statement shows the math. That statement is the entire basis of the agreement, which is why the documentation behind it has to hold up.

Example

Angela owed $94,000 after several years of uneven income. She could pay something every month, but nowhere near enough to clear the balance before her collection statutes expired.

Her representative prepared a complete financial statement showing limited disposable income, backed by documentation of her income, expenses, and assets. The IRS approved a Partial Pay Installment Agreement at a payment she could make. The balance she can’t pay will expire when the statutes run out.

What to Expect If You’re Approved

  • The IRS generally reviews the agreement about every two years and can raise the payment if your finances improve
  • Equity matters. The IRS may expect you to borrow against or sell an asset before it agrees to a partial payment
  • A Notice of Federal Tax Lien is likely
  • You have to stay current. File on time and pay on time every year the agreement is open, or it defaults

How We Can Help

Ron Friedman CPA evaluates whether a PPIA fits your numbers, prepares the financial statement and supporting documentation, negotiates the payment amount, and handles communication with the IRS so enforcement doesn’t start while your request is pending.

If you owe the IRS and a standard payment plan isn’t realistic, call Ron Friedman CPA at 914.712.6919 for a confidential consultation.

September 6, 2026Categories: income taxes, Installment Agreements, Offer in Compromise, Tax Resolution Strategies

Do You Owe Back Taxes? Why You Should Stop Panicking & Start Planning

May 19, 2022

If you owe back taxes to the IRS, some amount of panic is understandable. After all, the Internal Revenue Service has the power of the federal government in its corner, something no other debt collector can claim. They are considered the most brutal collection agency on the planet.

It is easy to freeze up and just do nothing when you owe back taxes to the IRS, but hiding from, or doing nothing about your tax debt will not make it go away. In fact, ignoring the taxes you owe will only make the situation worse, since interest and penalties can really add up. You also risk having your paycheck garnished (the IRS does not need a court order to do this) or your bank account levied. The IRS can also file a Notice of Federal Tax Lien making it all but impossible to obtain financing for a car or home.

So instead of panicking about your tax debt and hoping the problem will go away, you need to take some proactive steps. Now is not the time to panic and hide – now is the time to start taking action.

Some of these steps you can do on your own if you’d like, while others will likely require the intervention of an experienced tax resolution expert. Here are some proactive steps you can take to get a handle on your tax debt. If you need help resolving your IRS tax problem, contact us here Get help from Ron Friedman, CPA. We help people with IRS problems every day.

Confirm the Amount Owed

When you owe back taxes, one of the first things you should do is make sure you really owe the money. The IRS has been known to make mistakes, a lot of mistakes, and the agency is far from foolproof. Contact the IRS or have us do an IRS transcript analysis to determine the amount the IRS claims you owe.

Seek Out Deductions You May Have Missed

At the very least, you may not owe as much as you think you do, and every dollar you can remove from the bill is one more dollar in your favor. Now is the time to scour your past and current tax returns, looking for deductions and tax credits you might have missed.

Unless you are a seasoned tax expert, you will probably need some professional assistance to make this happen. If you are already working with a CPA or tax expert, you can ask them to look at your past tax returns but only a tax resolution expert, who helps people like you for a living, can protect your income and assets as you go through the process.

If you missed a few deductions and tax credits along the way, your tax professional can file amended returns on your behalf, lowering the amount of tax debt you owe – and possibly eliminating it altogether.  However, you usually can’t go back more than 3 years to amend returns.

Look for Special Programs You May Qualify For

 The bad news is the IRS wants its money and has the power to collect it.

The good news is the tax agency also offers several programs tax filers can use to make the repayment process easier. In some cases, the IRS may even be willing to settle for less, possibly much less, than the total amount of back taxes you owe.

These programs are not available to everyone, and if you have the resources needed to pay your back taxes, the IRS is unlikely to give you much of a break. But if your resources are limited, the tax agency may decide that a small amount of tax repayment is better than none at all.

The first step in the process is finding the programs for which you might qualify, and that will probably require the help of an experienced tax resolution expert.  Most CPAs do not have this experience. Negotiating with the IRS is not an easy thing to do, and you may need help to drive the best bargain and reduce your back taxes. In the end, it may be well worth paying a tax relief expert to negotiate on your behalf, especially if you end up with a much lower tax bill.

It is easy to panic when you owe back taxes, but you should not let fear get in your way. The longer you ignore the problem, the worse it is likely to get, and the sooner you act, the better off you, and your finances, will be. There is a solution to every IRS problem.  Let us see what IRS tax debt settlement programs you qualify for today. Get help from Ron Friedman, CPA.

May 19, 2022Categories: audit, back taxes, business taxes, filing taxes, garnishment, income taxes, Installment Agreements, IRS, IRS Fresh Start Program, Lien, Offer in Compromise, tax mistakes, tax notices, Tax Resolution Strategies, taxes

7 Reasons to Work with a Tax Resolution Professional to Resolve Your Back Taxes

May 11, 2022

When you owe money to the IRS, it is hard to think about anything else. While being in debt is never fun, no matter who the creditor is, the IRS enjoys almost unlimited power to collect the money they are due.

Unlike your mortgage lender or credit card company, the Internal Revenue Service has the power to attach your wages, raid your bank account and even take your freedom. No other creditor even comes close in terms of its power and influence, and taking on the agency on your own could be asking for trouble.

If you have received a notice from the IRS, you need to act fast, and you need the right assistance in your corner. Taking on the IRS requires specific expertise, and that is why it is so important to work with a quality tax resolution company. Here are seven reasons why working with a tax resolution specialist could save your good name – and your bank account.

  1. You gain specific expertise. The IRS is a specialized agency, and you need expert advice and guidance to get the most positive resolution.
  1. It will give you peace of mind. Just being contacted by the IRS can make your heart beat a bit faster, but working with a tax resolution expert can set your mind at ease once you hire a tax resolution specialist. Generally, once you hire a tax resolution expert you won’t have to meet or speak with the IRS. They will handle all communications and correspondence with the IRS. 
  1. The tax resolution process could save you a lot of money. Tax resolution professionals are experts at settlements, and working with one could save you a ton of money.
  1. Timely action could save your home and property. If you wait too long, you could put your home, business, bank accounts and personal property at risk. Time is of the essence when it comes to resolving tax issues, and timely assistance could make a world of difference.
  1. You will feel less alone. Few things feel as lonely as fighting the IRS on your own. When you work with a tax resolution expert, not only do you not have to go it alone but they actually step into your shoes to represent your best interests.
  1. You will have a chance to file missing returns. When faced with a big tax bill, it is easy to do nothing, but failing to file legally required tax returns could have serious consequences down the line. If you have years of unfiled returns, a tax resolution expert can help you catch up.
  1. You could save your credit score. Unresolved issues with the IRS will reflect badly on your credit report, lowering your credit score and making it harder to borrow money or qualify for a mortgage. Timely tax resolution could preserve your stellar credit score and help you avoid those serious consequences.

Owing money to the IRS can be pretty frightening. There is a reason those three letters strike so much fear into the hearts of ordinary citizens, even those who have done nothing wrong.

If you are in trouble with the IRS, you cannot afford to ignore the issue, so act fast and get the help you need today. Working with a tax resolution expert carries a host of benefits, starting with the nine outlined above.

Most likely, you wouldn’t go to court without a lawyer. Similarly, it’s best not to deal with the IRS without expert representation which can be provided by a tax resolution expert, who by training, is also a CPA, attorney or enrolled agent.

Reach out to our firm and we’ll schedule a no-obligation confidential case evaluation to explain your options in full to permanently resolve your tax problem. Get help from Ron Friedman, CPA.

May 11, 2022Categories: Accountants, income taxes, tax mistakes, tax planning, Tax Resolution Strategies, taxes

Tax Relief Options for Small Business Owners

February 14, 2022

If you are running a small business, you have an unwanted partner who will dig into your pocket every year, it’s the IRS. The IRS wants to know what you are doing, how much you are earning and most importantly how much you are paying in taxes. The tax agency is becoming increasingly aggressive in this regard. While the audit rate for individual returns has been hovering at far less than 1%, the audit rate for small businesses can be as much as 10 times higher.

It does not matter if you operate as a sole proprietor and use Schedule C to claim your income or if you are set up as a corporation (C or S), partnership or LLC/LLP – the IRS is watching what you do, and if they think you are not paying your fair share they will certainly come calling. When that demand letter from the IRS arrives, knowing what to do next can make all the difference, and the more you educate yourself the easier it will be to deal with, and eliminate, the tax debt.

Note: As a tax resolution firm, we always recommend that you reach out to a professional who knows how to aggressively negotiate and defend you against the IRS on your behalf. If you owe back taxes or are under audit, our firm can help negotiate with the IRS and potentially settle your tax debt. Call us today. Our tax resolution specialists can navigate the IRS maze so that you have nothing to worry about. Get help from Ron Friedman, CPA.

Small business owners are increasingly the target of enforcement efforts by the IRS, but the IRS does have some programs in place to make paying what those business owners owe easier. In some cases, those small business tax relief and tax resolution programs let you settle for less than what you owe but qualifying is not as straightforward as you might think.

For businesses that may be eligible, the assistance of a tax resolution specialist is absolutely critical. These experts can help guide you through the process and make sure you qualify, so you can rest a little easier and get back to building your business.

Payment Plans/Installment Agreements

If the amount your small business owes to the IRS is relatively small and you do not want to deal with additional hassles, it may make sense to pay the entire bill in full. If paying in full would be a hardship, the IRS does offer payment plans, and setting one up can make paying back what you owe easier and more financially palatable.

Keep in mind that interest will continue to accrue while the debt remains outstanding, and that is something to think about.

Offer In Compromise

If you’re under a lot of financial hardship, it may make more sense to try for

an offer in compromise (OIC), a special IRS program that could allow you to pay back less than you owe.

The offer in compromise program is a popular one with individual taxpayers and small business owners. If paying the entire amount would create a financial hardship for you, your family or your business, a tax resolution specialist can help you make the case to the IRS that you deserve a break.

What’s the best option?

Each of these options has its pros and cons, and it is important to understand how these programs work and who qualifies to use them. If your small business is in trouble with the IRS, taking the right action right away could reduce the amount you owe, give you some breathing room and allow you to focus on your clients – not on your taxes.

Running a small business has its challenges, but those difficulties are nothing compared to the stress and anxiety small business owners feel when dealing with the IRS. With so many small business owners now in IRS crosshairs, it has never been more important for freelancers, gig workers and the self-employed to have an advocate in their corner.

If you find yourself on the wrong end of an audit, a tax bill or an enforcement action from the IRS, the steps you take next are absolutely critical. Trying to take on the IRS on your own is a dangerous, and potentially expensive, thing to do, and you should always contact a tax resolution firm.

By working with an expert, you can gain access to vital information about small business settlement programs the IRS offers. You can gain access to the expertise you will need to settle your tax bill for less than you owe and get back in the good graces of the IRS. Time is of the essence when the IRS comes calling, and with the interest and penalty clock ticking you do not have one second to waste. So call us, your tax resolution expert, for a case evaluation. Get help from Ron Friedman, CPA

February 14, 2022Categories: back taxes, business owners, business taxes, filing taxes, income taxes, Installment Agreements, self employment, Tax Resolution Strategies, taxesTags: audit, Fresh Start, tax help, tax resolution

What Can the IRS Do to Collect Back Taxes?

January 11, 2022

Opening the mailbox and finding a letter from the IRS is frightening, but what happens next can be even scarier. The tax agency wields incredible power, and if they claim you owe additional taxes, they have many different options for forcing you to pay.
When the IRS claims you owe additional money, they will act quickly, and that could leave you reeling, and trying hard to preserve the money you need to pay your bills, feed your family and keep a roof over your head. If you are employed, the IRS can reach into your paycheck, forcing the company you work for to withhold part of what you are owed until the tax debt has been satisfied.

The IRS can also hold onto any refunds and government payments you would otherwise be due. If you have been waiting for that big fat refund check to arrive, you could be waiting a long time if you owe money to the IRS.

As if all this were not frightening enough, the tax agency also has the power to levy your bank accounts, including the accounts you need to run your business and your life. Those bank account freezes could leave you without the cash you need, putting you in a real bind and forcing you to pay back what you owe.

Your home could even be at risk if you owe money to the IRS. The tax agency could, for instance, apply for a lien against not only your primary residence but any other real estate you own. The threat of this kind of action has compelled many taxpayers to cough up the money the agency says they owe, even if they think the IRS is wrong.

As you can see, the IRS has wide latitude and plenty of power, and the tax agency is often unwilling to settle for less than the government says you owe. If you disagree with the amount the IRS is asking for, or if you simply do not have the money to pay the bill, you need to act fast. Ignoring the problem will only make it worse, and you cannot simply pretend that you never pulled that fateful envelope out of your home mailbox.

If you are on the wrong end of a compliance action by the IRS, you cannot afford to leave anything to chance, and you certainly should not try to fight back on your own. The tax code is complex, and far more pages than the Bible, and like that holy book, many of the terms are arcane and difficult to understand.

When fighting the IRS, you need the help of a professional, and that is where a tax resolution export comes into play. By working with a professional you can fight back on an even playing ground, and the money you save could be worth far more than the fee you pay.

Our firm specializes in tax resolution and helping people who owe the IRS or state $10,000 or more. We’ve seen taxpayers get blindsided every year by a huge tax bill and often falling behind on their taxes for years on end. If that’s you, we can help. Contact our firm today to discuss your tax debt settlement options.  Get help from Ron Friedman, CPA

January 11, 2022Categories: back taxes, filing taxes, garnishment, levy, Lien, Tax Resolution Strategies, taxes

Four Ways Freelancers and Gig Workers Can Trim Their Tax Bills

December 10, 2021

It is hard to beat the freedom and flexibility of freelancing and gig work. When you work for yourself, you can set your own hours, turn your home into an office and even ditch the daily commute.

All that is great, but there is one thing about freelancing that is much less pleasant. Compared to their corporate counterparts, self-employed individuals face an additional tax burden, an expense that takes many of them by surprise.

Note: If you end up falling behind on your taxes and the IRS or state claim you owe $10,000 or more, reach out to our tax resolution firm and we’ll schedule a free, no-obligation confidential consultation. Get help from Ron Friedman, CPA.

If you love the freedom of gig work but not the big tax bill, you need to think ahead. A little proactive planning can go a long way, so you can keep more of your hard-earned money in your pocket. Here are four smart strategies you can use to trim your tax liability and get more out of your freelancing and gig work.

#1. Fund a Health Savings Account

If you work for someone else, there is a good chance your boss picks up part of your health insurance costs, but freelancers and gig workers do not have that luxury. These self-employed individuals face additional challenges when it comes to health care, seeking affordable policies on the open market and saving money where they can.

One way the self-employed can save money and trim their tax bills is with a health savings account. Eligible individuals can contribute to a health savings account on a pre-tax basis, taking a serious tax deduction while making their health care more affordable. This tax savings can be a very big deal.

#2. Contribute to a Retirement Fund for the Self-Employed

Freelancers and gig workers need to look out for their own retirement, but there are plenty of options available. The annual contribution limits on retirement plans for the self-employed are among the most generous around, so you may be able to shelter a significant portion of your earnings from the tax man.

If you have a tax ID for your freelance business, you may be able to contribute to a solo 401(k). This plan works much the same as a traditional 401(k) plan, but the contribution limits could be even higher. Even if you do not have a tax ID, you can shelter part of your freelance or gig work income with a SEP-IRA or similar retirement plan.

#3. Take the Home Office Deduction

If you work out of your home, taking the home office deduction could save you a lot of money. If you are eligible for this valuable deduction, you could write off a portion of your property taxes and other home ownership costs, reducing your tax bill and keeping more money in your pocket.

There are specific rules regarding the home office deduction, so check with your tax preparer to make sure you qualify. If you can take the deduction, be sure to keep accurate records, and take photos of the office in your home.

#4. Push Income Into the Next Year

Freelance income can be notoriously unpredictable. One month is great, while the next is terrible. Yearly earnings can be just as variable, making tax planning difficult.

If you are having a particularly good year, you may be able to reduce your current tax bill by pushing some of that income into the following 12 months. When the end of the year approaches, delaying client invoices and moving income into the next year could save you money in the long run.

Once again, it is important to consult a tax professional before implementing this strategy. The IRS has established strict rules concerning income reporting, and you do not want to run afoul of the tax agency.

As a self-employed individual, you face some serious tax challenges, including the dreaded self-employment tax. That higher tax burden makes smart planning essential, and you can start that planning with the four tips listed above.

Owe Back Taxes and Need Tax Relief?

If you want an expert tax resolution specialist who knows how to navigate the IRS maze, reach out to our firm and we’ll schedule a no-obligation confidential consultation to explain your options to permanently resolve your tax problem Get help from Ron Friedman, CPA.

December 4, 2021Categories: back taxes, filing taxes, income, income taxes, IRS, retirement, retirement planning, Self Employed, self employment, tax mistakes, tax planning, tax records, Tax Resolution Strategies, taxesTags: 1099-MISC, freelance, reduce taxes, retirement, self employment, tax deduction, tax help

Tips for Finding a Qualified Tax Resolution Firm

October 22, 2021

Given how high the stakes are, it is surprising how little thought many people give to their taxes. All too often, individuals simply walk into a neighborhood storefront, hand over their most personal information and trust the person on the other side of the desk to do the right thing and prepare their taxes properly.

In many cases that trust is well placed, and the individual preparing the taxes is indeed the honest and trustworthy professional they claim to be. In other cases, however, the trust is misplaced, and the tax preparer will end up making mistakes that could cost the individual a great deal. If an audit is triggered by a deliberate misrepresentation or unintentional mistake, you will still be on the hook for any additional taxes, interest and penalties.

If you’re in tax trouble because you trusted the wrong tax preparer, then you will need a qualified tax resolution firm to help you resolve your tax problem. However, you don’t want to repeat the same mistake twice! So, it is important to do your homework and know what to look for in a tax resolution firm. Here are 4 quick tips to help you find a qualified tax resolution firm.

#1 Read Their Reviews Online

By reading online reviews you can quickly see if the tax resolution firm is reputable and stands by their clients. A lot of the big national firms will have terrible reviews but they market themselves heavily, so consumers don’t think twice about their reputation.

If you owe back taxes, waiting can cost you a lot of money and if the tax resolution firm disappears on you or doesn’t return your call, that wasted time could cost you dearly. This can easily be snuffed out by seeing if they have good online reviews about their services.

#2 Make Sure the Tax Resolution Firm Has Experience and A Proven Track Record

Negotiating with the IRS to settle your tax debt is a specialized skill that not all tax attorneys or tax professionals have. It’s important to ask about their recent case settlements and success stories. A true tax resolution professional will have proof they’ve done this before and successfully helped resolve back tax problems.

#3 What Does Their Communication Look Like Once You Sign On?

A professional and experienced firm will have systems in place to make sure you’re updated regularly on your tax resolution case. The IRS moves slow and there will likely be big gaps in time in between updates from the IRS. That doesn’t mean the tax relief firm should also have gaps in communication.

Ask how long they think it’ll take to resolve your tax problem, and how you’ll be updated even if they don’t have any news from the IRS.

#4 Avoid Big National Firms With Salespeople Who Promise The Moon But Don’t Deliver

You’ve heard their ads on the radio or TV. If you call a big national firm, you’ll likely get a salesperson who knows very little about taxes or how to settle your tax debt.

Not every taxpayer qualifies for all the IRS tax debt settlement programs. However, these salespeople will promise you the moon but will fail to deliver because they didn’t take the time to understand your specific situation and they’re not actually licensed tax resolution professionals.

Make sure to ask who will be responsible for your case and try to speak with them directly before signing up. A true tax resolution expert will be happy to speak with you to make sure they can understand your case and offer you the right solution.

Need Tax Relief?

If you want an expert tax resolution specialist who knows how to navigate the IRS maze, reach out to our firm and we’ll schedule a no-obligation confidential consultation to explain your options to permanently resolve your tax problem Get help from Ron Friedman, CPA.

October 22, 2021Categories: Accountants, audit, tax mistakes, tax notices, tax records, Tax Resolution Strategies, taxes

4 Common Tax Return Mistakes That Could Get You in Trouble with the IRS

As tax filing season unfolds, many taxpayers are taking the bull by the horns and doing their own taxes. Though it may seem like good news for the individual taxpayer, it’s important to watch out for common tax filing mistakes. Tax preparation software makes some errors like addition and subtraction blunders less likely, but even the best software cannot eliminate all potential problems and human error.

If you are getting ready to file your tax return, be sure to take a second (or third) look before you hit send. Keeping a close eye out for these common tax filing mistakes is the best way to ensure the IRS does not come knocking at your door.

Note: If you do get in trouble with the IRS and they claim you owe $10,o00 or more, reach out to our tax resolution firm and we’ll schedule a free, no-obligation confidential consultation to explain your options in full to permanently resolve your tax problem Get help from Ron Friedman, CPA.

That said, lets jump into the 4 common tax return mistakes that could land you in tax trouble.

#1. Transposed Numbers

If the 1099 you receive shows $6,300 in income and you inadvertently enter $3,600 instead, the IRS may see this as a tax dodge instead of an innocent mistake. At best, transposing numbers will slow down your refund and raise a red flag with the tax agency. At worst, it could trigger an audit or further examination of your entire return.

IRS computers are very good at comparing the figures taxpayers report to the ones they receive independently from banks, brokerage firms and other agencies. Be sure to double-check and verify every number you enter and make sure it is right. Your tax software can tell you if your numbers do not add up, but they cannot catch transposed figures.

#2. Misspelled Names

It is easy to misspell a name or transpose a Social Security number when entering dependent information, but doing so could cause real problems with your return. Be sure to double-check the names, ages and Social Security numbers of all your children before sending your return to the IRS.

Do not assume that all of that information will be transferred from a prior year return.

#3. Missing Social Security Numbers

It is easy to forget this vital piece of information, and doing so could delay your return and cause long-lasting problems. You may assume that your tax prep software will automatically enter your Social Security number, but that does not always happen.

Be sure to give your Social Security number (and that of your spouse) one last look before filing your return. That last minute check could save you a world of trouble later on.

#4. Not Reporting All Your Income or Taking Too Many Deductions

The IRS will likely get notified of income you received throughout the year, and it doesn’t just include your W2 wages. It’s important to keep track of all your income and report it to the IRS correctly to avoid any problems.

It can also be tempting to click a few extra boxes and input a few made up numbers as deductions to bring your tax liability down. DO NOT DO THIS. Just because the software lets you do this, doesn’t mean you should.

It’s not the software’s job to tell you whether or not you should be taking that extra deduction or write off, it’s the taxpayer’s job to be honest and file their tax returns correctly.

NEED TAX RELIEF?

If you made a mistake on your tax return and end up on the receiving end of an IRS notice, or if you have years of unfiled tax returns, reach out to our office. We’ll schedule a no-obligation confidential consultation to explain your options to permanently resolve your tax problem Get help from Ron Friedman, CPA.

October 22, 2021Categories: back taxes, filing taxes, IRS, Paystub, tax mistakes, tax notices, tax records, Tax Resolution Strategies, W-2

Does the IRS Disagree with Your Income Figures? 7 Critical Steps to Take Next

October 11, 2021

It is one of the scariest things that can befall a taxpayer – the dreaded notice from the IRS stating you owe them more money you can’t pay. When you open up the mailbox and see the return address of the tax agency staring back at you, your heart is bound to skip a beat (or two).

Few people look forward to communicating with the IRS, but plenty of taxpayers receive these notices every year. If you do find yourself on the receiving end of such a notice, knowing what to do next could make all the difference, and possibly save your bank account. Here are seven critical steps to take if the IRS disagrees with the income (or expense) figures you have reported.

Note: If you fall behind on filing your taxes, you’re not alone and we can help. Reach out to our tax resolution firm and we’ll help you file late tax returns and negotiate with the IRS if you owe back taxes. Get help from Ron Friedman, CPA.

  1. Stop panicking. Getting a letter from the IRS is enough to send your heart racing, but it is not the end of the world, and panic will not help you. Staying calm and reviewing the communication will be key, so settle your nerves and move on to the next steps.
  1. Review the document carefully. The letter you received from the IRS should clearly lay out where they disagree with your figures and what they used to come up with their own math. Reviewing these figures is the critical next step, and it is one you should take your time with.
  1. Pull a copy of the tax return in question. The communication you received from the IRS will tell you which year’s tax return is in question, so pulling a copy of that return should be your next step. Once you have the document in hand you can start to review the figures and see where the discrepancies came from.
  1. Find your supporting documents. In many cases these kinds of discrepancies are caused by simple errors like transposed numbers, so compare the figures on the supporting documents to what ended up on your return. You may find, for instance, that you reported interest of $2,150 as $1,250, and the solution could be as simple as ponying up the extra tax.
  1. Contact the best tax resolution firm. If you used a professional tax preparer, you might be tempted to talk to them first. That might be ok, but if you owe a large amount of back taxes, they might not be able to help. That’s where a good tax relief or tax resolution firm can help. The best tax relief firms can actually negotiate on your behalf with the IRS and find the best resolution for your tax situation, sometimes settling for less than what you owe in taxes!
  1. Review the response form. If you did make a mistake on your tax return, you can simply agree to the figures the IRS reported and pay the additional tax, along with any applicable penalties and interest. If you disagree, you can respond with the supporting documents that prove your case. Either way you will need to use the response form included with the letter, so review and complete that form carefully. We don’t suggest you do this yourself, instead, call our tax relief firm and make sure you investigate the issue in its entirety. Otherwise, you could land yourself in more trouble.
  1. Follow up. It can take some time for these kinds of discrepancies to be resolved, so you will need to bring a healthy dose of patience. If you agree with the notice and choose to pay the extra tax, you can see when your check is cashed or the money is taken out of your account, documenting the situation and keeping careful records. If you disagree, you will need to wait for the IRS to respond, but make sure you don’t assume the issue is resolved unless you have documentation stating that.

If you do need to contact the IRS, keep in mind that their phone lines are extremely busy. Many people who have been through this trauma recommend calling early in the morning, right after the phone lines open, so you can get in line and get your questions answer before the lines fill up.

We NEVER suggest our clients try to contact the IRS on their own. It would be like going to court without a lawyer. The IRS is not your friend, they’re sole responsibility in these cases is to collect taxes they think they’re owed.

Hopefully you will never be on the receiving end of a nasty letter from the IRS but it is still important to be prepared. If you do find a letter from the IRS in your mailbox, following the seven critical steps listed above could save you from further trouble. Reach out to our tax resolution firm and we’ll schedule a free, no-obligation confidential consultation to explain your options in full to permanently resolve your tax problem. Get help from Ron Friedman, CPA.

October 11, 2021Categories: filing taxes, IRS, tax mistakes, tax records, Tax Resolution Strategies, taxes

Posts pagination

Page 1 Page 2 Page 3 Next page

Recent Posts

  • When Paying the IRS Isn’t Possible: A Look at CNC Status
  • Can the IRS Take Your Retirement Accounts?
  • What Happens When the IRS Assigns a Revenue Officer to Your Case
  • Do Your Job, Do No Harm
  • The Coming Collection Squeeze

Archives

  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • July 2022
  • June 2022
  • May 2022
  • February 2022
  • January 2022
  • December 2021
  • November 2021
  • October 2021
  • August 2021
  • July 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • December 2020
  • October 2020
  • September 2020
  • August 2020
  • June 2020
  • January 2020
  • August 2019
  • July 2019
  • October 2016
  • September 2016
  • March 2016

Ron Friedman Tax Relief Pro

150 White Plains Road
Suite 310, Tarrytown, NY 10591
Tel: (914) 712-6919
Fax: (914) 631-0939
ron@ronfriedmancpa.com

Recent Posts

  • When Paying the IRS Isn’t Possible: A Look at CNC Status
  • Can the IRS Take Your Retirement Accounts?
  • What Happens When the IRS Assigns a Revenue Officer to Your Case

Servicing Areas

Westchester County, NY, Fairfield Cty, CT, New York City, The Bronx, Brooklyn, Queens, Staten Island, and surrounding areas.

IRS Circular 203 Disclosure: Any tax advice on this website (or any attachment hereto) is not intended or written to be used by any taxpayer for the purpose of avoiding penalties that may be imposed under U.S. tax law.
Facebook LinkedIn
© 2026 914 Tax. All Rights Reserved.